Research · Updated 9 Oct, 08:26 pm IST
Intern post asks if autoregressive diffusion can generate realistic market data
Why it matters for readers: If you follow AI and finance, this is an example of how generative models are being considered beyond images and text.
- The post frames market data as a stream of discrete events (orders added, cancelled, executed) that drive price evolution, not just continuous price series.1
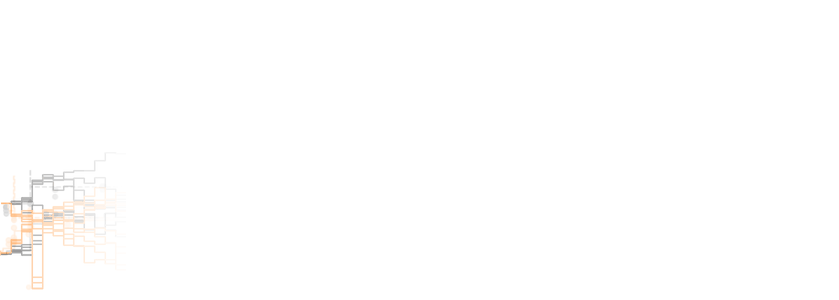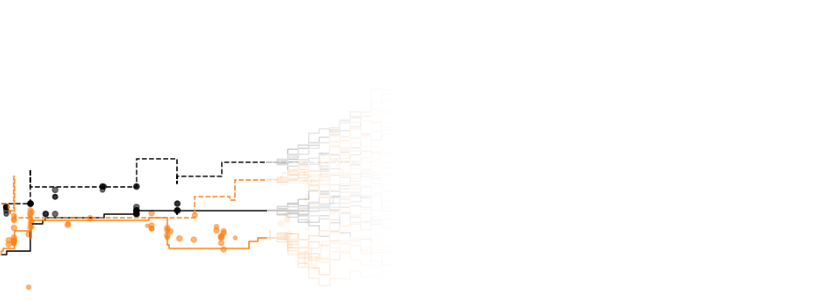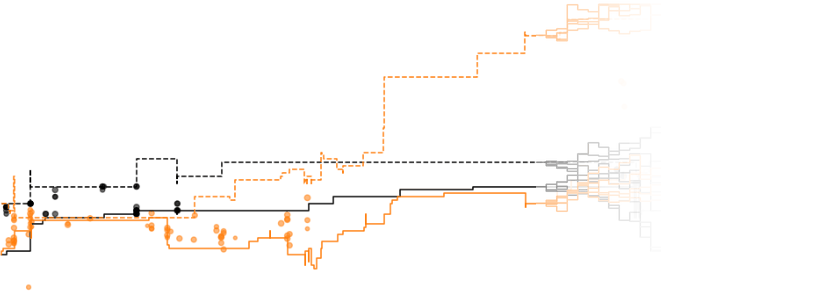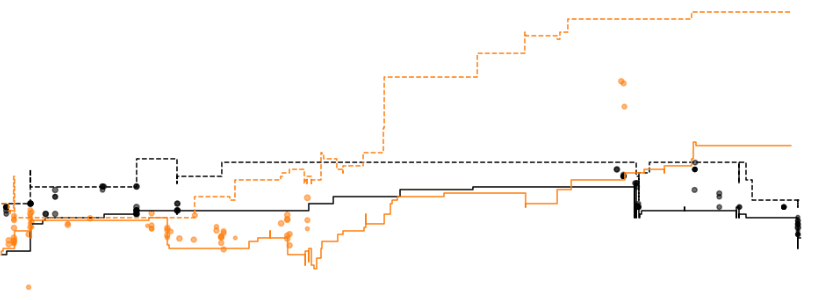
- It proposes autoregressive diffusion as a generative approach that could synthesize both event types and timing to produce textured rollouts beyond point-price predictions.1
- The author highlights that many order features (like price) have very high cardinality and that timing is a crucial continuous variable for generative models.1
- Practical market behaviors such as 'pennying' create spiky, structured distributions that complicate modeling choices between discrete and continuous representations.1
Get a brief like this every morning
Uzha reads hundreds of sources and gives you the stories that matter for your work, with every source linked. Free.
Get started